ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
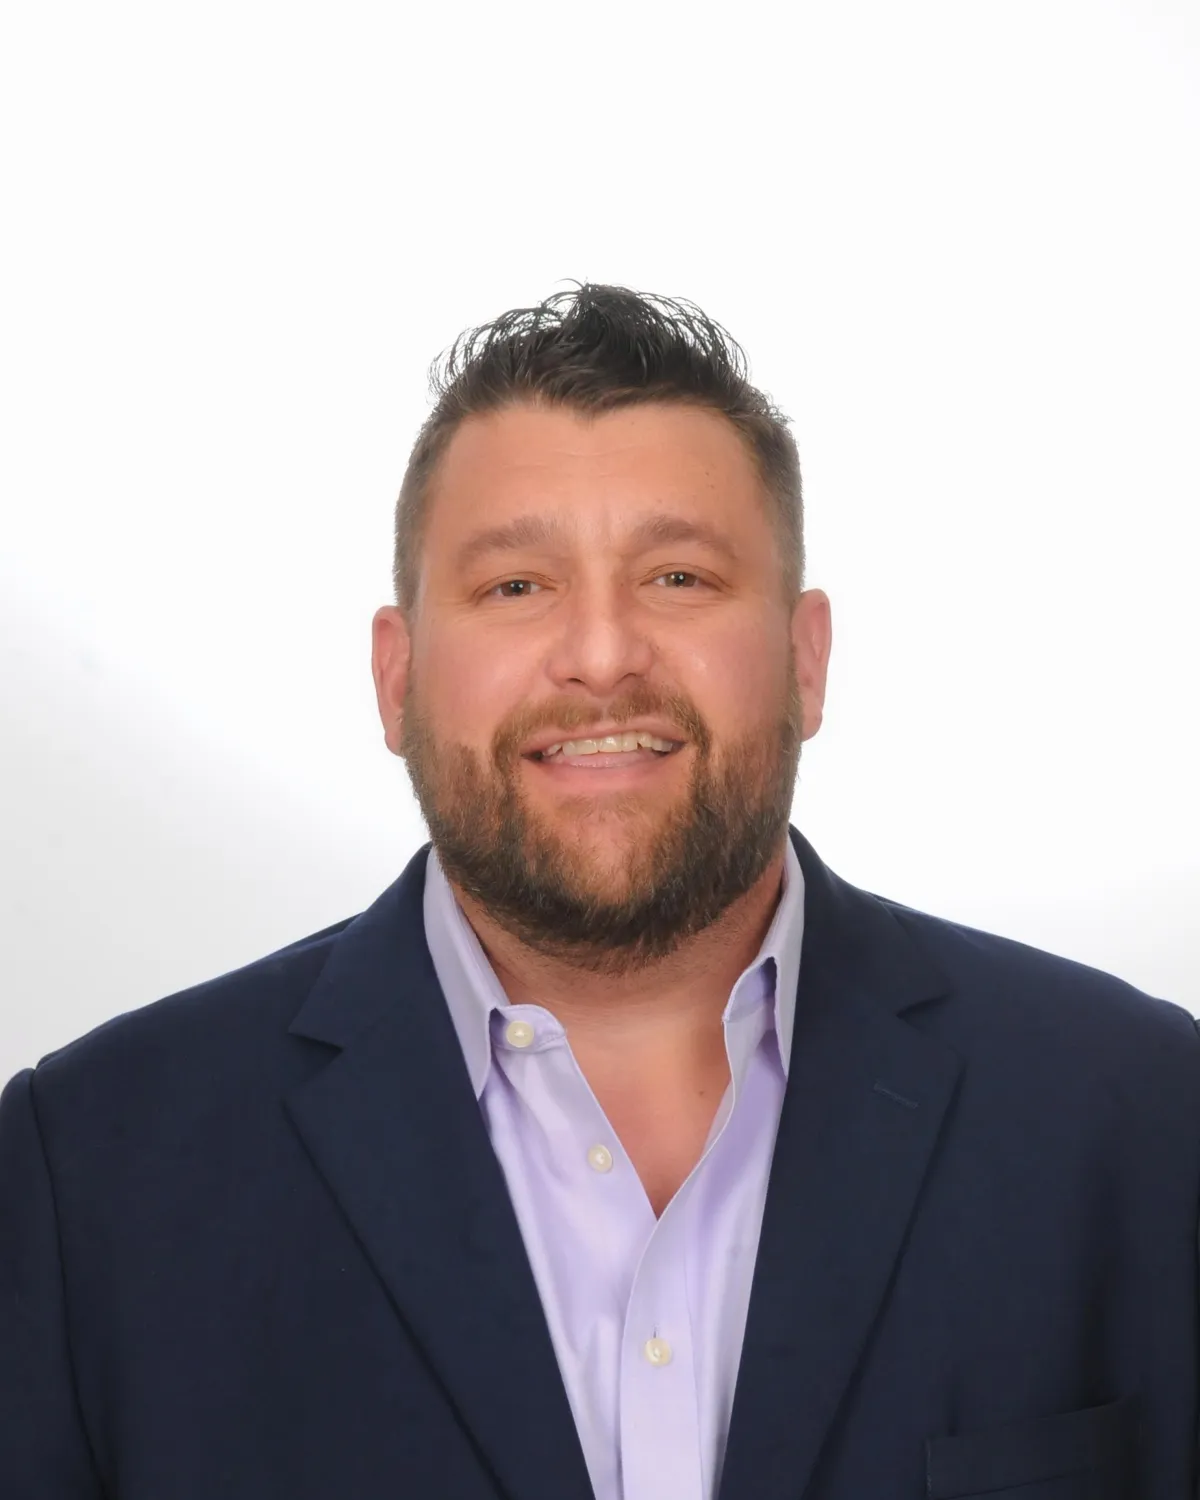
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
9 Things Every Dentist & Doctor Should Know About Mortgages
Brew up a great cup of coffee, pull out your notepads, iPads, MacBooks or whatever you prefer to take notes with—this post is epic and contains everything you ever wanted to know about physician loans. More importantly, you’ll find step-by-step information on how to research, compare banks and negotiate to get the best mortgage rates. Let’s go!
1. Physician Loans: A History Lesson
Special mortgage products for doctors are not new, but when you compare them with the modern mortgage market (popularized by insurance companies—not banks—in the 1930’s), they are relatively new products that have yet to make their way into the mainstream.
Sometime in the mid-2000’s, a forward-thinking employee at Bank of America (let’s call him Steve) honed in on an interesting strategy for attracting wealthy—or soon to be wealthy—clients to the bank.
Every single year, over 16,000 fresh-faced medical school grads were being matched to their residency/fellowship programs all over the United States. The majority of these new graduates had massive student loans. In fact, according to the Association of American Medical Colleges, the average medical student in 2015 will amass over $183,000 in debt. That figure is up 2% over 2014. If you look at this situation through a traditional lens, you understand why a recent graduate would never qualify for a traditional mortgage loan: too much debt and zero income history.
Most of these students also emerged into their adult life with the preconceived notion that renting an apartment or home is not a good idea. They would prefer to purchase a home, but can’t. Finally, Steve discovered that MDs have one of the lowest default rates (.02%) of any demographic, so it was relatively safe to lend them money.
That perfect storm created the doctor loan program.
Being an astute strategist and looking to add value to the bottom line, Steve brought this idea to the upper brass at the bank in Charlotte. It took a few months to consider the strategy, vet it out and get it approved. But once implemented, the program was hugely successful. It filled a much-needed void, so the bank generated millions and millions of dollars of new revenue by originating physician loans.
Competing banks took notice. They soon carved out similar doctor loan programs, complete with unique benefits, rates, and states where a resident could purchase a new home.
Now that we understand the history and how we got here, let’s take a look at what these loans look like in general.
2. A physician loan…
Requires you to invest very little money down for a down payment, usually zero to five percent of the total purchase price.
Accepts your residency/fellowship/employment contract as proof of how much money you will be making in the future. Usually, conventional mortgage underwriters look backward at your earning history in efforts to determine if you’ll be able to afford your monthly payment and not default.
Might call on you to open an account with the originating bank. Typically, they’ll need you to set up an auto-draft for your monthly payment, which lowers the risk of default. Forcing you to open an account is also a way for the bank to ensure you’ll be doing business other than your physician loan with them, with the hopes of converting you into a lifetime customer.
May be used by a resident or practicing physician. This is the case at 90% of the banks that offer physician loans. Make sure you inquire as soon as you can about this important distinction.Can be used on most property types (single family and townhomes), but in certain cities and regions, you may not be eligible to purchase a condo with a physician mortgage.
Does not distinguish between a conventional mortgage loan and a jumbo loan. Most banks will charge higher rates and fees on anything over $417,000, which is considered a riskier product, thus the name “jumbo”. A point of note: not all banks that offer the doctor loan program offer jumbo loans.
In some cases, lending guidelines may allow you to use money you receive as a gift for a down payment, cash reserves or miscellaneous closing costs.
Requires you to have decent credit. Typically, you need to be in the neighborhood of 700-720+. If you have scores that are over 800, congratulations. You’re in a different league, and the absolute best rates and terms for physician loans will be available to you.
Mandates that you have a loan payment to income ratio of less than 38%, which means your monthly payment can’t equate to more than 38% of your income. This can vary with lenders, though, and is something you should ask about for when interviewing different banks.
Let’s move on to the other mortgage type so you can easily compare the two.
3. Conventional conforming loans…
Require 3% to 5% down. For reference, 3% of a $200,000 loan would be $6,000. That is just what it takes to get in the door and qualify for the mortgage. This does not include any fees or percentages you’ll pay your Realtor.
Require PMI (private mortgage insurance) if you don’t put 20% down or have 20% equity in the home.
Allow you to qualify with a credit score of 580 or above.
Require three months of cash in reserve that could cover PITI (principal, interest, taxes and insurance) payments on the loan.
Require proof of earnings history (W-2 forms, bank statements, and/or pay stubs). If you’re self-employed, you’ll need to present two years of previous tax returns.
Use any debt (consumer, student, etc.) as factors in your debt-to-income ratios.
Require a debt-to-income ratio of 45% to 55%. This just means your debts can’t equate to more than 45% to 55% of your income.
Allow you to purchase condominiums in most markets.
Here comes the but…keep in mind not all banks can loan in every one of these areas, and each bank’s doctor loan program will be unique in each state. Some banks even vary rates and terms based on the particular city.
Caliber Home Loans makes Doctor loans in all 50 states.
4. These are your options :
There are many alternatives to physician loans. Let’s take a look at the main ones:
Conventional Mortgages – These are your typical mortgages, and encompass anything that isn’t part of a specific government loan or special program. They come in many flavors: 30, 20, 15 and 10 year fixed rate or 5/1, 7/1 and 10/1 adjustable rate mortgages (ARM). If you put at least 20% down, you’ll get a better interest rate and will not have to pay mortgage insurance. This is a good idea if you have the cash.
Many banks offer options for you to pay less than 20% down. The disadvantage of putting less money down are higher rates. If you’re not able to put 20% down, the bank will require you to pay PMI.
As of September 2016, you’ll have to put down at least 3% for this type of loan. Before the 2008 financial meltdown, there were many programs available that offered borrowers 100% financing. Those options have disappeared, many say with good reason.
FHA Loans – These loans are administered and regulated by the Federal Housing Authority. They allow for lower credit scores than conventional loans and require as little as 3.5% down. They also require private mortgage insurance (PMI) on all loans.
VA Loans – This program was created for US Military veterans and are guaranteed by the VA. They do not require a down payment or PMI, but there is an upfront fee (1.5% – 2% depending on your down payment) with most loans.
USDA Loans – Offered to rural, low-income borrowers, these mortgages require zero money down, are often cheaper than going the FHA route. They are sponsored and administered by the US Department of Agriculture and do require PMI.
State and Local Programs – These programs aim to help low to moderate income buyers purchase a home. Some are aimed at certain professions like teachers, firefighters and police officers. You can find out more and see if there is something available for doctors here. The last time I checked, there was not.
5. How to compare banks and their mortgages
It may seem like a daunting task, but putting the time into up-front research is well worth the end result. For example, on a $300,000 30-year fixed rate mortgage, reducing your interest rate by just .25% will save you almost $16,000 in interest payments over the life of your mortgage.
Call Caliber Home Loans who can shop your loan to ensure you get the best mortgage!
6. How mortgage rates are determined by banks
Before we get into negotiating rates, it’s helpful to understand how banks come up with the rates they charge borrowers for their home loans. This is a fascinating, complicated process. It’s not possible to say that interest rates are tied to one particular index, economic factor or governing body. It is possible to say that banks want to be as competitive as possible and at the same time as profitable as possible. This leads to the very strategic game that is determining their rates.
Things that influence rates include: the secondary mortgage market (how much investors are willing to pay for vast tranches—which are packaged bundles—of loans that are packaged up and sold as mortgage-backed securities), inflation rates, the price of US Treasuries, the LIBOR Bank rate and the Federal Reserve funds rate.
7. Finding the perfect home
There are many guides online that can help you define what will make the perfect home for you. HTGV, Forbes, and Houzz have put together some nice ones. Do this first, because it’s important to narrow your possibilities and focus on homes that fit your criteria.
Once you know what you’re looking for, be prepared to do a lot of virtual house-hunting. Things have changed a lot since your parents drove around with their Realtor to look at every single house they were interested in. Be very glad about that.
8. Buying a house isn’t a good idea for everyone
Let’s be honest. Sometimes, it just makes more sense to rent. If you’re not sure about where you’ll be in three years, rent. If you think you’re in a declining market, and there’s a possibility that home prices will decrease, rent. We’ve come up with a guide to help you weigh these factors: Getting a Physician Loan vs. Renting. The New York Times also put together a great interactive article called Is it Better to Rent or Buy?
In many cases, it makes more sense to buy. From a financial and psychological perspective, the benefits of homeownership are pretty compelling.
If you are saddled with consumer debt and/or excessive student loans, you also might want to pay off some of those debts before purchasing real estate, even with a physician mortgage loan. It all depends on the interest rates and terms. Check out this post on debt from Future Proof M.D. for more info and a few options.
Think about it and choose the path that is right for you.
9. You need to educate yourself
Our physician mortgage loan FAQ will answer more of your burning questions about physician loans specifically, but it’s critical you learn as much as you can about the finance and home buying process. This is the biggest purchase you’ll ever make, and it pays dividends to know what you’re doing. At least know the basics. You’ll probably buy another house in your lifetime, and you can continue to build on your home buying knowledge with every purchase.
Heck. You may even be able to pass this knowledge down to your friends, family or children one day. It’s important stuff.
Please comment below and let me know if there are other things you’d like to know. If you spot any mistakes, point them out, and I’ll correct them.
My best advice to you is to give Bill Rapp, the Mortgage Viking, a call today to discuss the next steps: 281-222-0433.
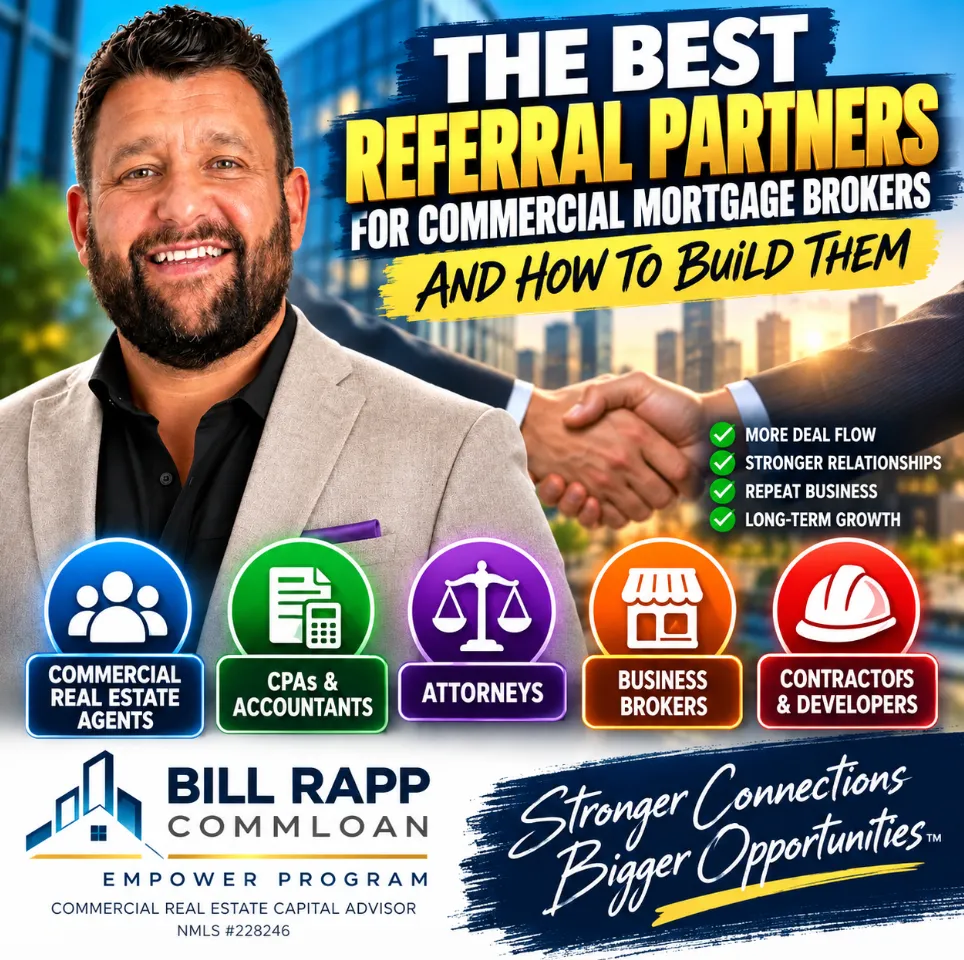
🏢 The Best Referral Partners for Commercial Mortgage Brokers—and How to Build Them 🤝
🏢 The Best Referral Partners for Commercial Mortgage Brokers—and How to Build Them 🤝
🤝 Commercial Mortgage Broker Lead Generation: Build Referral Partners Who Create More Deal Flow 📈
________________________________________________________________________________
The Best Referral Partners for Commercial Mortgage Brokers—and How to Build Them
Commercial mortgage brokerage is fundamentally a relationship business.
Technology can help identify lenders. Marketing can generate inquiries. Advertising can create awareness. But some of the strongest commercial real estate financing opportunities still originate from something much simpler: a trusted professional making an introduction.
For commercial mortgage brokers, building a strong referral network can create a consistent pipeline of borrowers who already have a degree of trust before the first financing conversation begins.
The key is not simply meeting more people. It is developing relationships with professionals who regularly encounter commercial real estate owners, investors and business owners who need capital.
Why Referral Partners Matter in Commercial Mortgage Brokerage
Commercial financing needs often emerge during another transaction or business decision.
An investor may be preparing to acquire a property. A business owner may be considering buying the building they currently lease. An accountant may identify an upcoming balloon payment. An attorney may be working on a partnership restructuring. A commercial real estate broker may have a buyer who needs financing before submitting an offer.
In each situation, someone else may recognize the financing need before the borrower ever contacts a commercial mortgage broker.
That makes referral relationships an important component of commercial mortgage broker lead generation.
A productive referral network can potentially provide:
·More qualified introductions
·Earlier involvement in transactions
·Better-prepared borrowers
·More consistent deal flow
·Opportunities for repeat business
·Stronger professional relationships
The objective should not be collecting contacts. It should be becoming a useful financing resource to professionals whose clients periodically need capital.
1. Commercial Real Estate Brokers
Commercial real estate brokers can be natural referral partners because financing and real estate transactions are closely connected.
Investment sales brokers may have buyers who need acquisition financing. Tenant representatives may work with business owners considering an owner-occupied purchase. Listing brokers may encounter buyers who need help understanding financing before making an offer.
A capital advisor can add value by helping evaluate questions such as:
How much can the property support?
What DSCR will a lender require?
How much equity will the borrower need?
Would conventional, SBA, bridge or another financing structure make sense?
The earlier these questions are addressed, the easier it may be to identify potential financing obstacles before they threaten the transaction.
2. CPAs and Accountants
CPAs often have extensive visibility into their clients' businesses, investments and financial objectives.
They may know when a client is preparing to purchase a building, refinance debt, acquire another business, expand operations or make a major capital investment.
That makes accountants potentially valuable referral partners for commercial mortgage brokers.
The relationship should be reciprocal in value. Rather than repeatedly asking a CPA for referrals, become a resource who can help their clients understand commercial financing options, lender requirements and the financial implications of different capital structures.
3. Commercial Real Estate Attorneys
Commercial real estate attorneys are frequently involved in transactions long before financing closes.
They may assist with purchase agreements, entity formation, partnership agreements, title matters, leases and transaction structuring.
These situations can reveal financing requirements.
Building relationships with commercial real estate attorneys can therefore create opportunities for introductions while also giving the mortgage broker a trusted legal resource when borrowers need appropriate counsel.
4. Business Brokers
Business acquisitions frequently involve more than simply purchasing a company.
A transaction may include real estate, equipment, inventory, goodwill, renovations or working capital.
That creates opportunities for financing structures such as SBA 7(a), SBA 504, conventional commercial financing and other business-purpose loan programs.
A commercial mortgage broker who understands the complete capital stack can become a useful partner for business brokers trying to get acquisitions across the finish line.
5. Contractors, Builders and Developers
Construction and development projects create financing needs at multiple stages.
A client might need land financing, construction financing, bridge capital, permanent financing or a refinance after stabilization.
Contractors and developers frequently know about these projects well before a lender becomes involved.
Commercial mortgage brokers who develop relationships within the construction and development community may gain access to financing opportunities earlier in the project's lifecycle.
6. Residential Mortgage Professionals
Residential mortgage professionals can also be valuable commercial referral partners.
Their clients may own rental portfolios, operate businesses, purchase commercial properties or need financing outside the residential lender's product scope.
Instead of turning those opportunities away, a residential mortgage professional can refer the commercial transaction to a trusted commercial financing specialist while maintaining the original client relationship.
The same principle works in reverse. Commercial mortgage brokers routinely encounter clients who need residential financing and can refer those opportunities back.
7. Bankers and Credit Union Relationship Managers
This one surprises some people.
Banks can be excellent referral sources for commercial mortgage brokers.
A bank may like the borrower but be unable to approve a particular transaction because of property type, loan size, leverage, concentration limits, geographic restrictions, underwriting policy or another credit parameter.
A commercial mortgage broker with access to a broader lender marketplace may be able to explore alternatives.
Maintaining relationships with bankers can therefore create a mutually beneficial solution: the banker preserves the broader relationship while the borrower gets another avenue for financing.
How Do You Actually Build Strong Referral Partnerships?
The first principle is simple:
Do not build the relationship around asking for leads. Build it around creating value.
Learn what your referral partner does, who they serve and what types of problems they regularly encounter.
Then make yourself useful.
Share relevant financing information. Explain changes in lender requirements. Help evaluate difficult scenarios. Make introductions when appropriate. Refer business when possible.
Most importantly, protect their relationship with the client.
If someone refers a borrower to you, communicate professionally, respond quickly and keep the referring professional informed when appropriate and authorized.
Your performance reflects on the person who made the introduction.
Make It Easy to Refer Business to You
Referral partners need to understand exactly what you do.
"I'm a commercial mortgage broker" may be too broad.
Instead, clearly explain the types of financing situations you can evaluate.
For example:
Commercial real estate acquisitions. Refinances. Cash-out transactions. Owner-occupied properties. Investment properties. Multifamily. SBA financing. Bridge loans. Construction and other business-purpose real estate financing.
The clearer your positioning, the easier it becomes for someone to recognize an opportunity and think of you.
Become a Resource Before You Need the Referral
One of the strongest ways to build referral relationships is to provide value before asking for anything.
If a commercial broker has a buyer who is unsure how much they can borrow, help analyze the financing.
If a CPA has a client facing a balloon payment, help estimate refinance proceeds.
If a business broker has a complicated acquisition, help evaluate the capital stack.
Not every conversation will become a loan.
That is okay.
Consistently demonstrating expertise can build the credibility that produces future introductions.
Use Technology Without Losing the Relationship
Technology can dramatically improve commercial mortgage brokerage.
Through the CommLoan Empower Program, I can use technology and lender-marketplace resources to evaluate commercial financing opportunities across a broad range of potential capital sources.
But technology does not replace relationships.
It strengthens what an advisor can do after the introduction occurs.
The referral partner provides trust and context. The financing platform expands the ability to evaluate potential lending solutions. The advisor connects the two.
The Compounding Effect of a Referral Network
A strong referral network does not have to contain hundreds of people.
A smaller group of productive relationships can generate meaningful deal flow.
Imagine developing strong relationships with several commercial real estate brokers, CPAs, attorneys, business brokers, bankers and developers.
Each professional works with numerous clients throughout the year.
Instead of constantly searching for individual borrowers, you are building relationships with people who regularly encounter borrowers.
That is where referral-based commercial mortgage lead generation can begin to compound.
Final Takeaway
The best referral partners for commercial mortgage brokers are not simply people with large contact lists.
They are professionals who regularly encounter commercial real estate investors and business owners at the moment a financing need develops.
Build those relationships by becoming useful.
Understand their business. Provide financing expertise. Communicate well. Protect their client relationships. Refer opportunities back when appropriate.
Over time, strong professional partnerships can produce something far more valuable than a single transaction:
a repeatable source of relationships, introductions and commercial loan opportunities.
Need Help Evaluating a Commercial Financing Opportunity?
I'm Bill Rapp with the CommLoan Empower Program.
If you are a commercial real estate professional, CPA, attorney, business broker, banker, developer—or simply have a client who needs commercial financing—I would be happy to evaluate the scenario and help identify potential financing options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246