ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
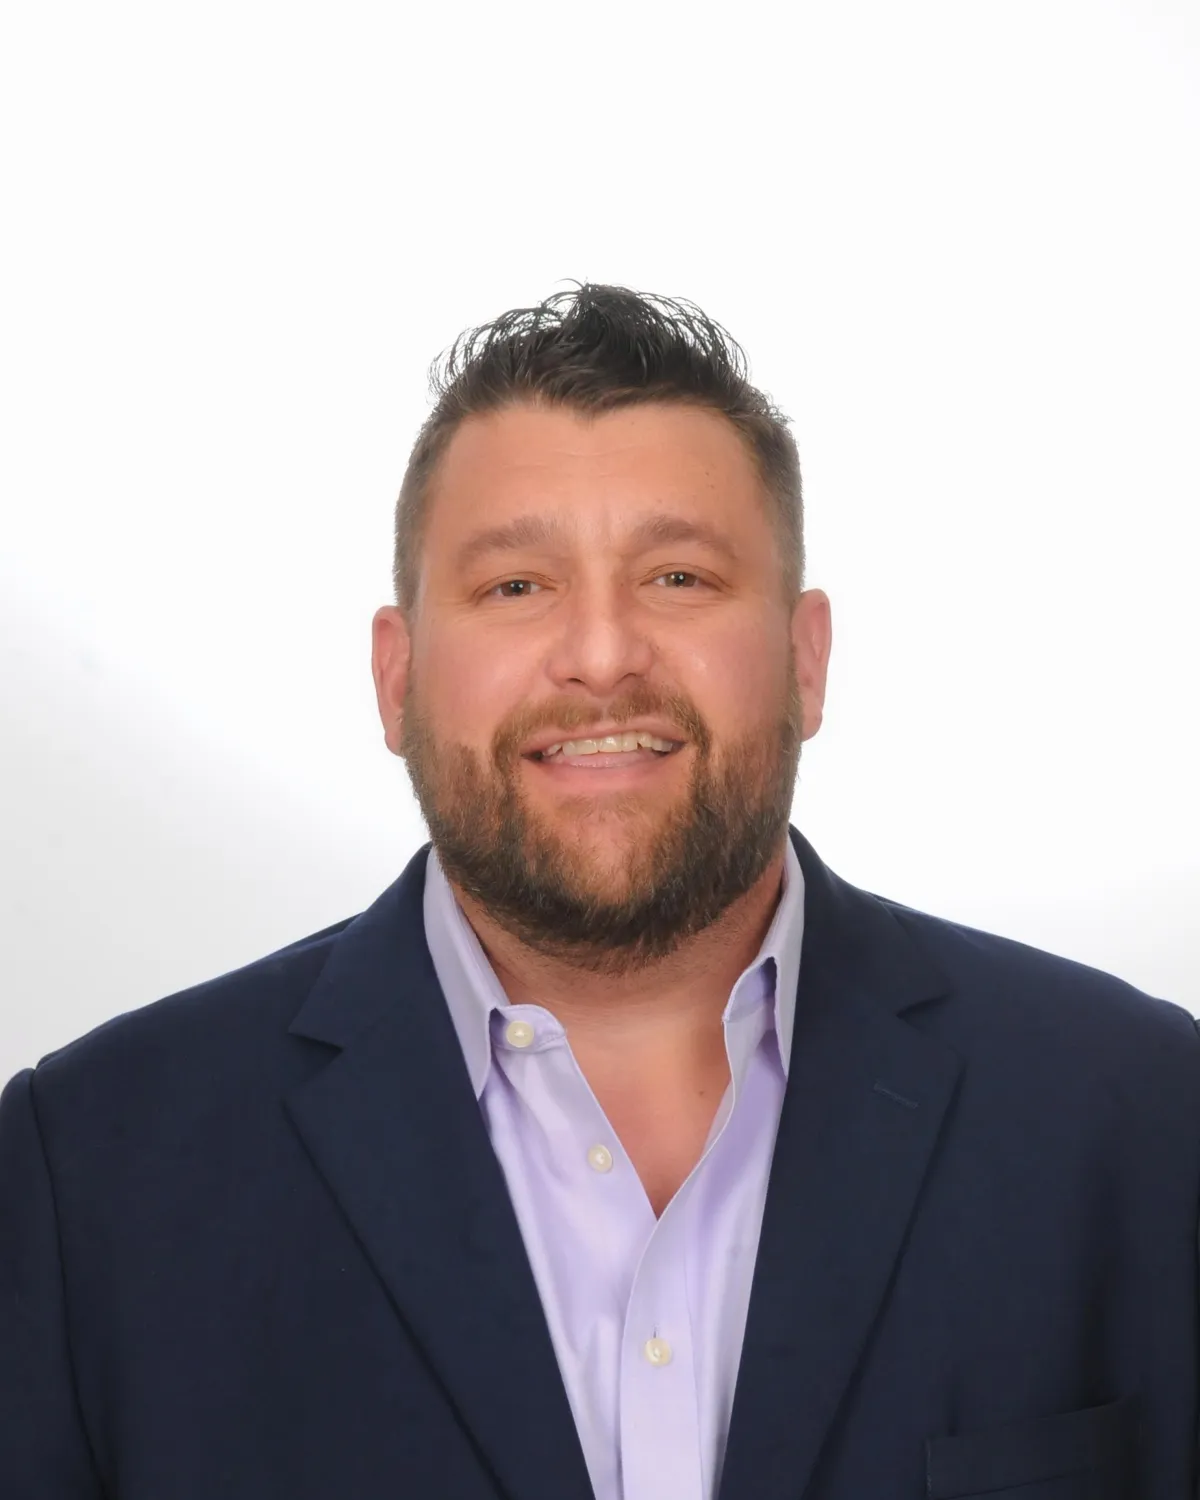
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
9 Things Every Dentist & Doctor Should Know About Mortgages
Brew up a great cup of coffee, pull out your notepads, iPads, MacBooks or whatever you prefer to take notes with—this post is epic and contains everything you ever wanted to know about physician loans. More importantly, you’ll find step-by-step information on how to research, compare banks and negotiate to get the best mortgage rates. Let’s go!
1. Physician Loans: A History Lesson
Special mortgage products for doctors are not new, but when you compare them with the modern mortgage market (popularized by insurance companies—not banks—in the 1930’s), they are relatively new products that have yet to make their way into the mainstream.
Sometime in the mid-2000’s, a forward-thinking employee at Bank of America (let’s call him Steve) honed in on an interesting strategy for attracting wealthy—or soon to be wealthy—clients to the bank.
Every single year, over 16,000 fresh-faced medical school grads were being matched to their residency/fellowship programs all over the United States. The majority of these new graduates had massive student loans. In fact, according to the Association of American Medical Colleges, the average medical student in 2015 will amass over $183,000 in debt. That figure is up 2% over 2014. If you look at this situation through a traditional lens, you understand why a recent graduate would never qualify for a traditional mortgage loan: too much debt and zero income history.
Most of these students also emerged into their adult life with the preconceived notion that renting an apartment or home is not a good idea. They would prefer to purchase a home, but can’t. Finally, Steve discovered that MDs have one of the lowest default rates (.02%) of any demographic, so it was relatively safe to lend them money.
That perfect storm created the doctor loan program.
Being an astute strategist and looking to add value to the bottom line, Steve brought this idea to the upper brass at the bank in Charlotte. It took a few months to consider the strategy, vet it out and get it approved. But once implemented, the program was hugely successful. It filled a much-needed void, so the bank generated millions and millions of dollars of new revenue by originating physician loans.
Competing banks took notice. They soon carved out similar doctor loan programs, complete with unique benefits, rates, and states where a resident could purchase a new home.
Now that we understand the history and how we got here, let’s take a look at what these loans look like in general.
2. A physician loan…
Requires you to invest very little money down for a down payment, usually zero to five percent of the total purchase price.
Accepts your residency/fellowship/employment contract as proof of how much money you will be making in the future. Usually, conventional mortgage underwriters look backward at your earning history in efforts to determine if you’ll be able to afford your monthly payment and not default.
Might call on you to open an account with the originating bank. Typically, they’ll need you to set up an auto-draft for your monthly payment, which lowers the risk of default. Forcing you to open an account is also a way for the bank to ensure you’ll be doing business other than your physician loan with them, with the hopes of converting you into a lifetime customer.
May be used by a resident or practicing physician. This is the case at 90% of the banks that offer physician loans. Make sure you inquire as soon as you can about this important distinction.Can be used on most property types (single family and townhomes), but in certain cities and regions, you may not be eligible to purchase a condo with a physician mortgage.
Does not distinguish between a conventional mortgage loan and a jumbo loan. Most banks will charge higher rates and fees on anything over $417,000, which is considered a riskier product, thus the name “jumbo”. A point of note: not all banks that offer the doctor loan program offer jumbo loans.
In some cases, lending guidelines may allow you to use money you receive as a gift for a down payment, cash reserves or miscellaneous closing costs.
Requires you to have decent credit. Typically, you need to be in the neighborhood of 700-720+. If you have scores that are over 800, congratulations. You’re in a different league, and the absolute best rates and terms for physician loans will be available to you.
Mandates that you have a loan payment to income ratio of less than 38%, which means your monthly payment can’t equate to more than 38% of your income. This can vary with lenders, though, and is something you should ask about for when interviewing different banks.
Let’s move on to the other mortgage type so you can easily compare the two.
3. Conventional conforming loans…
Require 3% to 5% down. For reference, 3% of a $200,000 loan would be $6,000. That is just what it takes to get in the door and qualify for the mortgage. This does not include any fees or percentages you’ll pay your Realtor.
Require PMI (private mortgage insurance) if you don’t put 20% down or have 20% equity in the home.
Allow you to qualify with a credit score of 580 or above.
Require three months of cash in reserve that could cover PITI (principal, interest, taxes and insurance) payments on the loan.
Require proof of earnings history (W-2 forms, bank statements, and/or pay stubs). If you’re self-employed, you’ll need to present two years of previous tax returns.
Use any debt (consumer, student, etc.) as factors in your debt-to-income ratios.
Require a debt-to-income ratio of 45% to 55%. This just means your debts can’t equate to more than 45% to 55% of your income.
Allow you to purchase condominiums in most markets.
Here comes the but…keep in mind not all banks can loan in every one of these areas, and each bank’s doctor loan program will be unique in each state. Some banks even vary rates and terms based on the particular city.
Caliber Home Loans makes Doctor loans in all 50 states.
4. These are your options :
There are many alternatives to physician loans. Let’s take a look at the main ones:
Conventional Mortgages – These are your typical mortgages, and encompass anything that isn’t part of a specific government loan or special program. They come in many flavors: 30, 20, 15 and 10 year fixed rate or 5/1, 7/1 and 10/1 adjustable rate mortgages (ARM). If you put at least 20% down, you’ll get a better interest rate and will not have to pay mortgage insurance. This is a good idea if you have the cash.
Many banks offer options for you to pay less than 20% down. The disadvantage of putting less money down are higher rates. If you’re not able to put 20% down, the bank will require you to pay PMI.
As of September 2016, you’ll have to put down at least 3% for this type of loan. Before the 2008 financial meltdown, there were many programs available that offered borrowers 100% financing. Those options have disappeared, many say with good reason.
FHA Loans – These loans are administered and regulated by the Federal Housing Authority. They allow for lower credit scores than conventional loans and require as little as 3.5% down. They also require private mortgage insurance (PMI) on all loans.
VA Loans – This program was created for US Military veterans and are guaranteed by the VA. They do not require a down payment or PMI, but there is an upfront fee (1.5% – 2% depending on your down payment) with most loans.
USDA Loans – Offered to rural, low-income borrowers, these mortgages require zero money down, are often cheaper than going the FHA route. They are sponsored and administered by the US Department of Agriculture and do require PMI.
State and Local Programs – These programs aim to help low to moderate income buyers purchase a home. Some are aimed at certain professions like teachers, firefighters and police officers. You can find out more and see if there is something available for doctors here. The last time I checked, there was not.
5. How to compare banks and their mortgages
It may seem like a daunting task, but putting the time into up-front research is well worth the end result. For example, on a $300,000 30-year fixed rate mortgage, reducing your interest rate by just .25% will save you almost $16,000 in interest payments over the life of your mortgage.
Call Caliber Home Loans who can shop your loan to ensure you get the best mortgage!
6. How mortgage rates are determined by banks
Before we get into negotiating rates, it’s helpful to understand how banks come up with the rates they charge borrowers for their home loans. This is a fascinating, complicated process. It’s not possible to say that interest rates are tied to one particular index, economic factor or governing body. It is possible to say that banks want to be as competitive as possible and at the same time as profitable as possible. This leads to the very strategic game that is determining their rates.
Things that influence rates include: the secondary mortgage market (how much investors are willing to pay for vast tranches—which are packaged bundles—of loans that are packaged up and sold as mortgage-backed securities), inflation rates, the price of US Treasuries, the LIBOR Bank rate and the Federal Reserve funds rate.
7. Finding the perfect home
There are many guides online that can help you define what will make the perfect home for you. HTGV, Forbes, and Houzz have put together some nice ones. Do this first, because it’s important to narrow your possibilities and focus on homes that fit your criteria.
Once you know what you’re looking for, be prepared to do a lot of virtual house-hunting. Things have changed a lot since your parents drove around with their Realtor to look at every single house they were interested in. Be very glad about that.
8. Buying a house isn’t a good idea for everyone
Let’s be honest. Sometimes, it just makes more sense to rent. If you’re not sure about where you’ll be in three years, rent. If you think you’re in a declining market, and there’s a possibility that home prices will decrease, rent. We’ve come up with a guide to help you weigh these factors: Getting a Physician Loan vs. Renting. The New York Times also put together a great interactive article called Is it Better to Rent or Buy?
In many cases, it makes more sense to buy. From a financial and psychological perspective, the benefits of homeownership are pretty compelling.
If you are saddled with consumer debt and/or excessive student loans, you also might want to pay off some of those debts before purchasing real estate, even with a physician mortgage loan. It all depends on the interest rates and terms. Check out this post on debt from Future Proof M.D. for more info and a few options.
Think about it and choose the path that is right for you.
9. You need to educate yourself
Our physician mortgage loan FAQ will answer more of your burning questions about physician loans specifically, but it’s critical you learn as much as you can about the finance and home buying process. This is the biggest purchase you’ll ever make, and it pays dividends to know what you’re doing. At least know the basics. You’ll probably buy another house in your lifetime, and you can continue to build on your home buying knowledge with every purchase.
Heck. You may even be able to pass this knowledge down to your friends, family or children one day. It’s important stuff.
Please comment below and let me know if there are other things you’d like to know. If you spot any mistakes, point them out, and I’ll correct them.
My best advice to you is to give Bill Rapp, the Mortgage Viking, a call today to discuss the next steps: 281-222-0433.
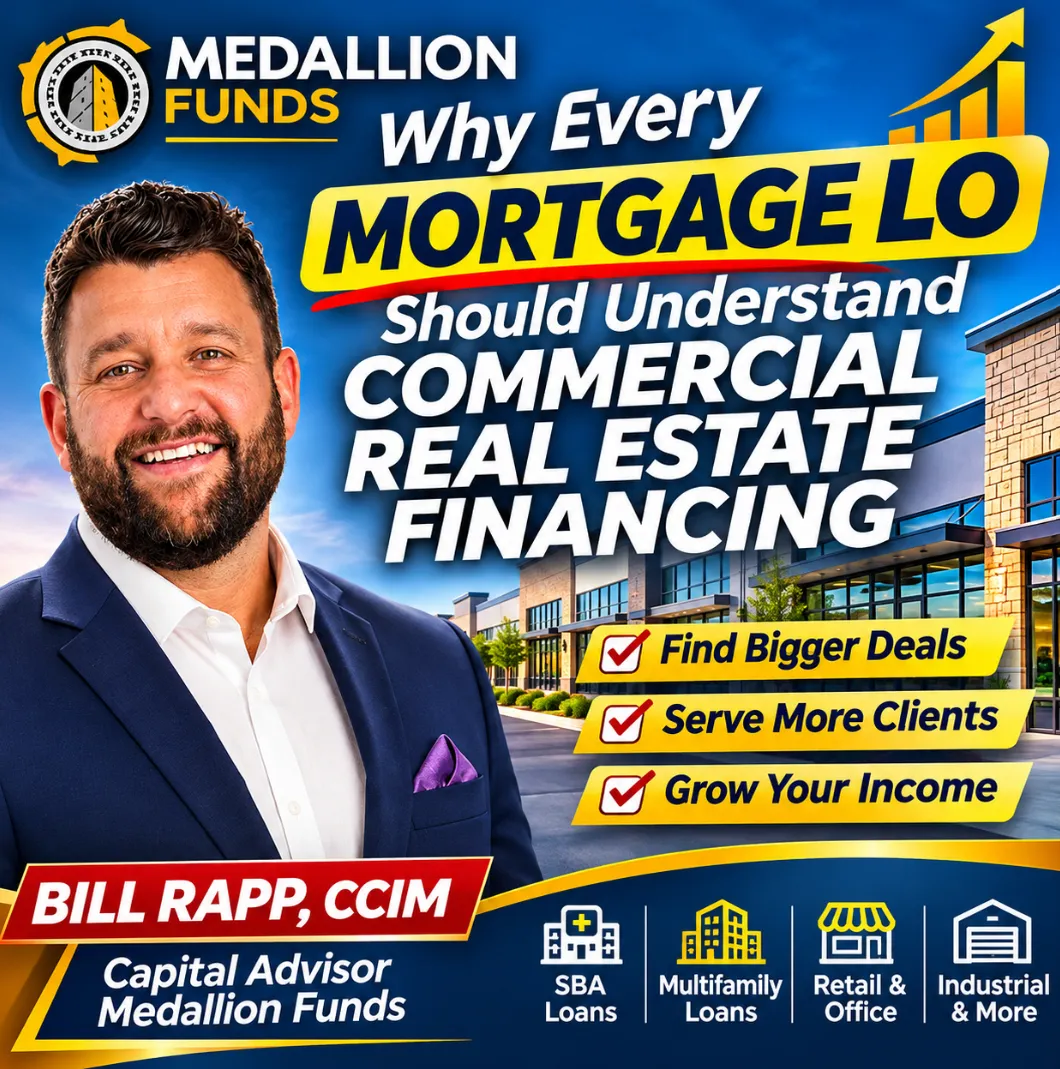
🚀 Why Mortgage Loan Officers Should Learn Commercial Lending 💰
🚀 Why Mortgage Loan Officers Should Learn Commercial Lending 💰
🏢 Commercial Lending: The Opportunity Mortgage LOs Overlook 🚀
__________________________________________________________________________
Why Every Mortgage LO Should Understand Commercial Real Estate Financing
Commercial real estate financing for mortgage loan officers is more than an additional lending specialty. It is an opportunity to expand client relationships, understand more financing solutions, and potentially develop new revenue streams.
Most residential mortgage loan officers spend their careers helping clients purchase homes, refinance mortgages, or access home equity. Those services are essential, but they represent only part of the lending market.
What happens when your client wants to purchase a medical office building, finance a warehouse, refinance an apartment complex, or acquire a retail center?
If you only understand residential mortgages, you may not recognize the financing opportunity.
That is why every mortgage loan officer should develop a working knowledge of commercial real estate lending.
At Medallion Funds, we believe mortgage professionals can create stronger businesses by understanding both residential and commercial financing.
1. Commercial Lending Expands Your Mortgage Business
Traditional residential mortgage lending focuses primarily on individual borrowers and residential properties.
Commercial real estate financing introduces an entirely different set of opportunities.
Commercial financing may include:
·Office buildings and medical facilities
·Retail shopping centers and restaurants
·Industrial warehouses and flex properties
·Apartment buildings and multifamily investments
·Owner-occupied business properties
·Mixed-use developments
·Commercial construction and renovation projects
·Investment property acquisitions and refinancing
For mortgage loan officers, understanding these transactions creates opportunities to serve clients beyond their primary residences.
The same person purchasing a home today could become a commercial property investor or business owner tomorrow.
Developing commercial mortgage knowledge helps you recognize those opportunities before the client looks elsewhere.
2. Your Existing Clients May Already Need Commercial Loans
One of the biggest misconceptions about commercial mortgage lending is that you need an entirely new client base.
In reality, commercial financing opportunities may already exist within your residential mortgage relationships.
Consider these examples.
Doctors and Dentists
A physician purchasing a primary residence may eventually want to acquire a medical office building.
A dentist might decide to purchase the building currently occupied by their practice rather than continue leasing.
Depending on eligibility, SBA financing or conventional owner-occupied commercial financing may provide solutions.
Small Business Owners
Your self-employed mortgage clients may also own restaurants, service companies, retail businesses, or industrial operations.
These clients may need financing to purchase business real estate, expand operations, or refinance existing commercial debt.
Real Estate Investors
A client who begins with one rental property may eventually acquire a portfolio of single-family rentals or a five-unit apartment building.
As their investments expand, their financing requirements may shift from conventional residential loans to DSCR, portfolio, or commercial mortgage programs.
High-Net-Worth Borrowers
Affluent residential mortgage clients may also own investment properties, development projects, or commercial buildings.
Understanding commercial financing allows loan officers to identify these potential needs and coordinate with qualified lending specialists.
The opportunity is not necessarily finding more clients. It may be identifying additional financing needs among the clients you already know.
3. Understand the Five Major Commercial Financing Options
Mortgage loan officers do not need to become commercial underwriting experts overnight.
However, they should understand the primary commercial lending categories.
SBA 7(a) and SBA 504 Loans
SBA financing can help eligible small businesses purchase or improve owner-occupied commercial real estate.
SBA 7(a) loans may support real estate, equipment, working capital, and qualifying business acquisitions, subject to program rules.
SBA 504 financing is commonly used for qualifying fixed assets, including owner-occupied buildings and major equipment.
These programs can be particularly relevant to doctors, dentists, manufacturers, and business owners.
Conventional Commercial Mortgages
Banks, credit unions, and other lenders provide commercial mortgages for qualifying income-producing and owner-occupied properties.
Underwriting typically considers property cash flow, borrower financial strength, collateral value, liquidity, and repayment capacity.
DSCR and Investment Property Loans
Debt Service Coverage Ratio, or DSCR, measures how effectively qualifying property income covers required debt payments.
For commercial real estate, lenders often calculate DSCR using net operating income divided by annual debt service.
Some residential investment property DSCR programs use different qualifying calculations.
Understanding the distinction helps mortgage loan officers recognize investor financing opportunities.
Commercial Bridge Loans
Bridge loans provide shorter-term financing for certain acquisitions, renovations, lease-up strategies, or transitional properties.
They may offer flexibility when conventional financing is unavailable, but borrowers must understand the higher costs, maturity dates, and refinancing risks that can accompany these loans.
Commercial Construction Loans
Commercial construction financing can support eligible ground-up development and major renovation projects.
These loans commonly involve construction budgets, project feasibility, draw schedules, borrower equity, and completion requirements.
Knowing which financing category may fit a client's transaction is often the first step toward creating value.
4. Commercial Loan Underwriting Is Different From Residential Lending
Residential mortgage underwriting typically focuses heavily on the borrower's income, credit, assets, debt-to-income ratio, and property value.
Commercial underwriting often adds another dimension: the property's ability to generate sufficient cash flow.
Important commercial lending concepts include:
Loan-to-Value (LTV): The loan amount compared with the property's appraised or accepted value.
Debt Service Coverage Ratio (DSCR): The relationship between qualifying property income and required debt payments.
Net Operating Income (NOI): Property operating income after ordinary operating expenses, but before debt service and certain other items.
Debt Yield: NOI divided by the loan amount, expressed as a percentage.
Loan Term vs. Amortization: A commercial loan may amortize over 25 years but mature in five years, leaving a substantial balloon payment.
Commercial lenders may also evaluate tenant quality, lease expiration schedules, property condition, environmental risks, sponsor experience, and liquidity.
Understanding these fundamentals helps mortgage loan officers ask better questions and refer commercial opportunities appropriately.
5. Commercial Financing Can Strengthen Referral Relationships
Real estate agents, CPAs, financial advisors, attorneys, and business owners frequently encounter commercial financing questions.
A mortgage loan officer who understands both residential and commercial lending can become a more useful referral resource.
For example:
·A residential real estate agent may have a client buying a small apartment building.
·A CPA may work with a business owner considering a commercial property acquisition.
·A financial advisor may have an investor seeking to refinance commercial assets.
·A builder may need a construction financing resource.
·A dentist may need financing for a new practice location.
When you understand the financing possibilities, you can help connect these professionals with the right resources.
This can support deeper, more durable professional relationships.
6. Commercial Loans May Create Additional Income Opportunities
Commercial mortgages frequently involve larger loan balances than individual residential mortgages.
For example, consider a residential mortgage loan of $400,000 compared with a commercial acquisition loan of $2,000,000.
The commercial loan is five times larger.
However, a larger loan does not automatically mean five times the compensation.
Commercial financing compensation varies based on the lender, transaction structure, brokerage agreement, licensing requirements, and applicable law.
Some mortgage professionals may originate eligible commercial loans directly. Others may participate through an authorized referral or collaboration arrangement.
The appropriate structure depends on the professional's experience, licensing, company policies, and the transaction.
The real opportunity is developing another potential business channel while maintaining appropriate compliance and client service.
7. Real-World Example: A Dentist Who Wants to Own the Building
Imagine you are a residential mortgage loan officer who recently helped a dentist purchase a $750,000 home.
Six months later, the dentist mentions paying $12,000 per month to lease office space.
The dentist is considering purchasing a $2 million medical office property.
A residential-only loan officer might simply recommend contacting a local bank.
But an LO familiar with commercial financing knows to ask several important questions:
·Will the dental practice occupy the required percentage of the property?
·What is the business's operating history and cash flow?
·How much equity is available?
·Would SBA 7(a), SBA 504, or conventional financing be appropriate?
·Does the dentist plan to occupy the property long term?
The answers help determine which financing programs may be worth evaluating.
Instead of losing the opportunity, the loan officer can introduce an appropriate commercial financing specialist or participate where authorized.
The client receives more comprehensive guidance, and the loan officer strengthens an existing relationship.
8. How Residential Mortgage LOs Can Start Learning Commercial Lending
You do not need to abandon residential mortgages to explore commercial financing.
Start with a practical approach.
Step 1: Learn the terminology. Understand NOI, DSCR, LTV, debt yield, balloon payments, and amortization.
Step 2: Identify your existing client opportunities. Look for business owners, doctors, dentists, and real estate investors.
Step 3: Understand the major programs. Become familiar with SBA, conventional commercial, DSCR, bridge, and construction financing.
Step 4: Build commercial lending relationships. Work with experienced capital advisors and commercial lending specialists.
Step 5: Understand compliance and compensation. Confirm that your licensing, company policies, and applicable laws permit your intended role.
Step 6: Expand gradually. Begin by identifying potential transactions and helping clients reach qualified professionals.
The objective is not to become an expert in every commercial property type.
It is to become knowledgeable enough to recognize opportunities and guide clients toward appropriate financing solutions.
9. Why Medallion Funds Is Relevant to Mortgage Loan Officers
At Medallion Funds, we work across residential and commercial financing solutions.
Our approach emphasizes lender relationships, financing alternatives, underwriting knowledge, and collaboration.
Mortgage professionals exploring commercial lending may benefit from learning how to evaluate transactions involving:
·Residential investment properties
·Small multifamily buildings
·Owner-occupied commercial real estate
·Medical and dental offices
·Retail and industrial properties
·Commercial acquisitions and refinances
·Business-purpose and construction financing
Commercial lending is not a substitute for a successful residential mortgage business.
It is a complementary area of expertise that may help mortgage professionals serve a broader range of clients.
Final Thoughts: Become More Than a Residential Mortgage Resource
Mortgage loan officers operate in a competitive environment.
Interest rates change. Housing markets fluctuate. Borrower demand shifts.
Developing commercial real estate financing knowledge can help mortgage professionals diversify their expertise, deepen referral relationships, and identify additional business opportunities.
You do not need to originate every commercial loan yourself.
You need to understand enough to recognize the opportunity and know whom to involve.
The mortgage professionals who understand both residential and commercial financing may be better positioned to serve clients throughout their real estate investment journey.
Connect With Bill Rapp, CCIM
I'm Bill Rapp, CCIM, Capital Advisor with Medallion Funds.
If you're a mortgage loan officer interested in learning more about commercial lending opportunities, lender resources, or expanding your mortgage business, let's connect.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246