ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
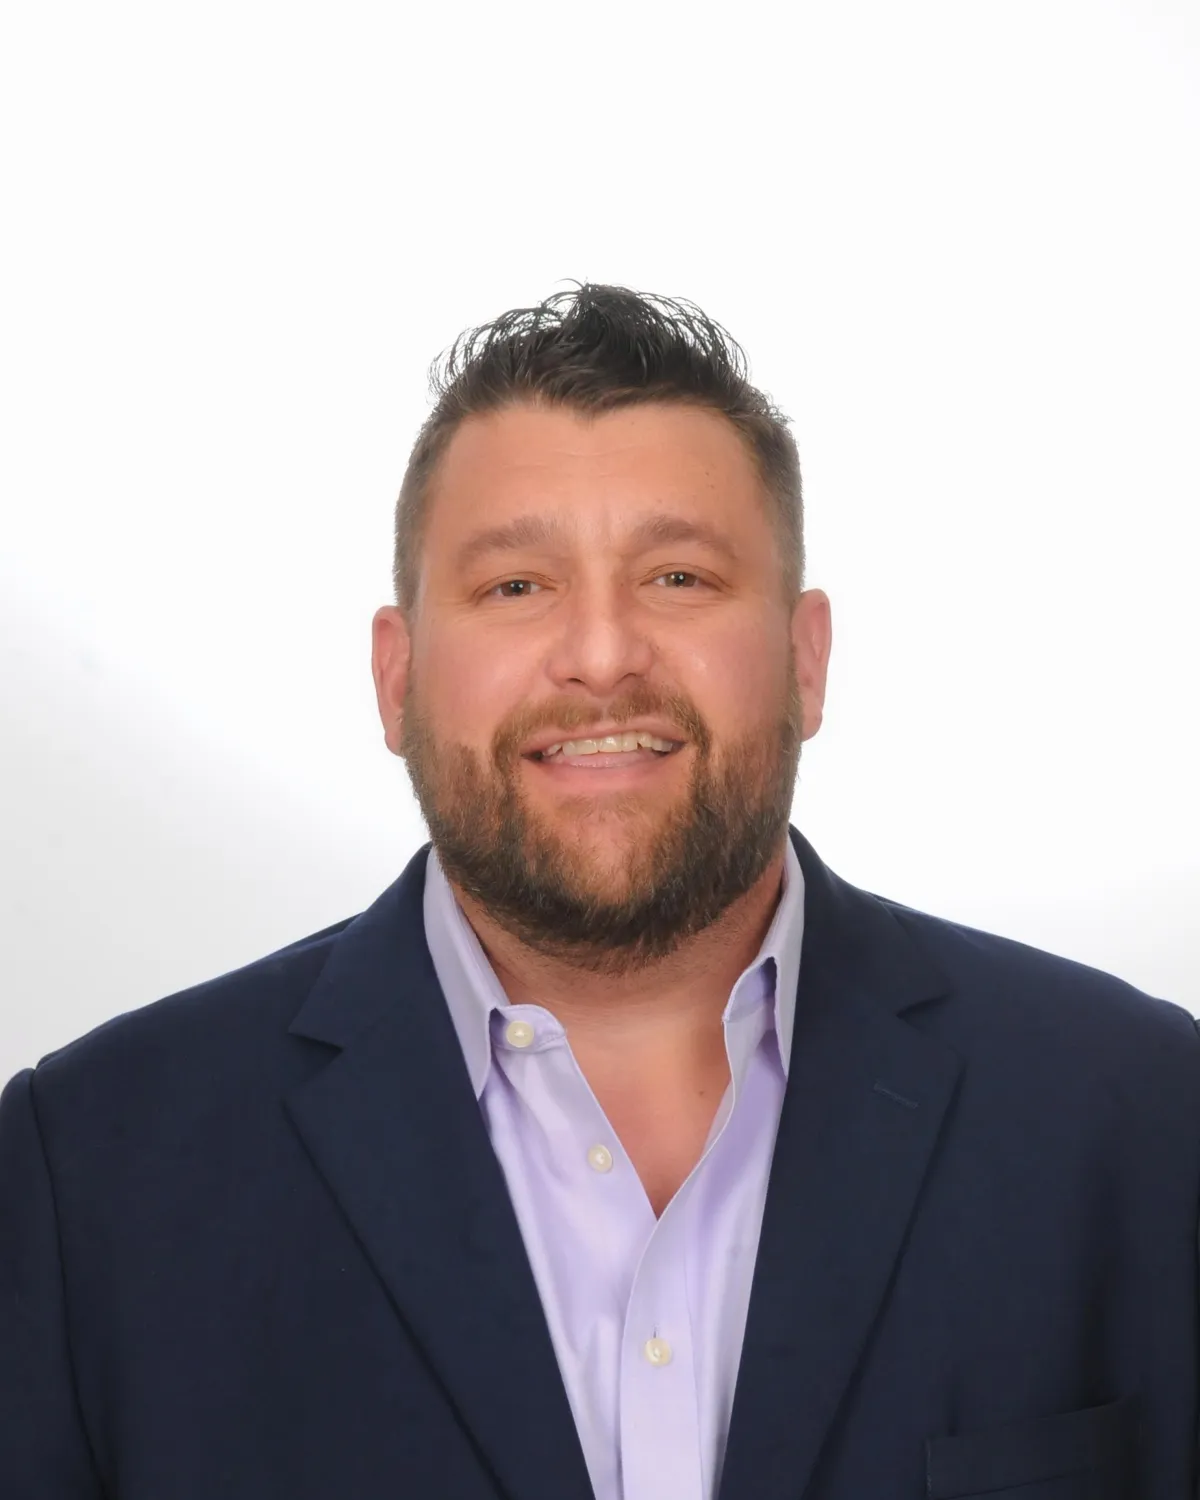
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
9 Things Every Dentist & Doctor Should Know About Mortgages
Brew up a great cup of coffee, pull out your notepads, iPads, MacBooks or whatever you prefer to take notes with—this post is epic and contains everything you ever wanted to know about physician loans. More importantly, you’ll find step-by-step information on how to research, compare banks and negotiate to get the best mortgage rates. Let’s go!
1. Physician Loans: A History Lesson
Special mortgage products for doctors are not new, but when you compare them with the modern mortgage market (popularized by insurance companies—not banks—in the 1930’s), they are relatively new products that have yet to make their way into the mainstream.
Sometime in the mid-2000’s, a forward-thinking employee at Bank of America (let’s call him Steve) honed in on an interesting strategy for attracting wealthy—or soon to be wealthy—clients to the bank.
Every single year, over 16,000 fresh-faced medical school grads were being matched to their residency/fellowship programs all over the United States. The majority of these new graduates had massive student loans. In fact, according to the Association of American Medical Colleges, the average medical student in 2015 will amass over $183,000 in debt. That figure is up 2% over 2014. If you look at this situation through a traditional lens, you understand why a recent graduate would never qualify for a traditional mortgage loan: too much debt and zero income history.
Most of these students also emerged into their adult life with the preconceived notion that renting an apartment or home is not a good idea. They would prefer to purchase a home, but can’t. Finally, Steve discovered that MDs have one of the lowest default rates (.02%) of any demographic, so it was relatively safe to lend them money.
That perfect storm created the doctor loan program.
Being an astute strategist and looking to add value to the bottom line, Steve brought this idea to the upper brass at the bank in Charlotte. It took a few months to consider the strategy, vet it out and get it approved. But once implemented, the program was hugely successful. It filled a much-needed void, so the bank generated millions and millions of dollars of new revenue by originating physician loans.
Competing banks took notice. They soon carved out similar doctor loan programs, complete with unique benefits, rates, and states where a resident could purchase a new home.
Now that we understand the history and how we got here, let’s take a look at what these loans look like in general.
2. A physician loan…
Requires you to invest very little money down for a down payment, usually zero to five percent of the total purchase price.
Accepts your residency/fellowship/employment contract as proof of how much money you will be making in the future. Usually, conventional mortgage underwriters look backward at your earning history in efforts to determine if you’ll be able to afford your monthly payment and not default.
Might call on you to open an account with the originating bank. Typically, they’ll need you to set up an auto-draft for your monthly payment, which lowers the risk of default. Forcing you to open an account is also a way for the bank to ensure you’ll be doing business other than your physician loan with them, with the hopes of converting you into a lifetime customer.
May be used by a resident or practicing physician. This is the case at 90% of the banks that offer physician loans. Make sure you inquire as soon as you can about this important distinction.Can be used on most property types (single family and townhomes), but in certain cities and regions, you may not be eligible to purchase a condo with a physician mortgage.
Does not distinguish between a conventional mortgage loan and a jumbo loan. Most banks will charge higher rates and fees on anything over $417,000, which is considered a riskier product, thus the name “jumbo”. A point of note: not all banks that offer the doctor loan program offer jumbo loans.
In some cases, lending guidelines may allow you to use money you receive as a gift for a down payment, cash reserves or miscellaneous closing costs.
Requires you to have decent credit. Typically, you need to be in the neighborhood of 700-720+. If you have scores that are over 800, congratulations. You’re in a different league, and the absolute best rates and terms for physician loans will be available to you.
Mandates that you have a loan payment to income ratio of less than 38%, which means your monthly payment can’t equate to more than 38% of your income. This can vary with lenders, though, and is something you should ask about for when interviewing different banks.
Let’s move on to the other mortgage type so you can easily compare the two.
3. Conventional conforming loans…
Require 3% to 5% down. For reference, 3% of a $200,000 loan would be $6,000. That is just what it takes to get in the door and qualify for the mortgage. This does not include any fees or percentages you’ll pay your Realtor.
Require PMI (private mortgage insurance) if you don’t put 20% down or have 20% equity in the home.
Allow you to qualify with a credit score of 580 or above.
Require three months of cash in reserve that could cover PITI (principal, interest, taxes and insurance) payments on the loan.
Require proof of earnings history (W-2 forms, bank statements, and/or pay stubs). If you’re self-employed, you’ll need to present two years of previous tax returns.
Use any debt (consumer, student, etc.) as factors in your debt-to-income ratios.
Require a debt-to-income ratio of 45% to 55%. This just means your debts can’t equate to more than 45% to 55% of your income.
Allow you to purchase condominiums in most markets.
Here comes the but…keep in mind not all banks can loan in every one of these areas, and each bank’s doctor loan program will be unique in each state. Some banks even vary rates and terms based on the particular city.
Caliber Home Loans makes Doctor loans in all 50 states.
4. These are your options :
There are many alternatives to physician loans. Let’s take a look at the main ones:
Conventional Mortgages – These are your typical mortgages, and encompass anything that isn’t part of a specific government loan or special program. They come in many flavors: 30, 20, 15 and 10 year fixed rate or 5/1, 7/1 and 10/1 adjustable rate mortgages (ARM). If you put at least 20% down, you’ll get a better interest rate and will not have to pay mortgage insurance. This is a good idea if you have the cash.
Many banks offer options for you to pay less than 20% down. The disadvantage of putting less money down are higher rates. If you’re not able to put 20% down, the bank will require you to pay PMI.
As of September 2016, you’ll have to put down at least 3% for this type of loan. Before the 2008 financial meltdown, there were many programs available that offered borrowers 100% financing. Those options have disappeared, many say with good reason.
FHA Loans – These loans are administered and regulated by the Federal Housing Authority. They allow for lower credit scores than conventional loans and require as little as 3.5% down. They also require private mortgage insurance (PMI) on all loans.
VA Loans – This program was created for US Military veterans and are guaranteed by the VA. They do not require a down payment or PMI, but there is an upfront fee (1.5% – 2% depending on your down payment) with most loans.
USDA Loans – Offered to rural, low-income borrowers, these mortgages require zero money down, are often cheaper than going the FHA route. They are sponsored and administered by the US Department of Agriculture and do require PMI.
State and Local Programs – These programs aim to help low to moderate income buyers purchase a home. Some are aimed at certain professions like teachers, firefighters and police officers. You can find out more and see if there is something available for doctors here. The last time I checked, there was not.
5. How to compare banks and their mortgages
It may seem like a daunting task, but putting the time into up-front research is well worth the end result. For example, on a $300,000 30-year fixed rate mortgage, reducing your interest rate by just .25% will save you almost $16,000 in interest payments over the life of your mortgage.
Call Caliber Home Loans who can shop your loan to ensure you get the best mortgage!
6. How mortgage rates are determined by banks
Before we get into negotiating rates, it’s helpful to understand how banks come up with the rates they charge borrowers for their home loans. This is a fascinating, complicated process. It’s not possible to say that interest rates are tied to one particular index, economic factor or governing body. It is possible to say that banks want to be as competitive as possible and at the same time as profitable as possible. This leads to the very strategic game that is determining their rates.
Things that influence rates include: the secondary mortgage market (how much investors are willing to pay for vast tranches—which are packaged bundles—of loans that are packaged up and sold as mortgage-backed securities), inflation rates, the price of US Treasuries, the LIBOR Bank rate and the Federal Reserve funds rate.
7. Finding the perfect home
There are many guides online that can help you define what will make the perfect home for you. HTGV, Forbes, and Houzz have put together some nice ones. Do this first, because it’s important to narrow your possibilities and focus on homes that fit your criteria.
Once you know what you’re looking for, be prepared to do a lot of virtual house-hunting. Things have changed a lot since your parents drove around with their Realtor to look at every single house they were interested in. Be very glad about that.
8. Buying a house isn’t a good idea for everyone
Let’s be honest. Sometimes, it just makes more sense to rent. If you’re not sure about where you’ll be in three years, rent. If you think you’re in a declining market, and there’s a possibility that home prices will decrease, rent. We’ve come up with a guide to help you weigh these factors: Getting a Physician Loan vs. Renting. The New York Times also put together a great interactive article called Is it Better to Rent or Buy?
In many cases, it makes more sense to buy. From a financial and psychological perspective, the benefits of homeownership are pretty compelling.
If you are saddled with consumer debt and/or excessive student loans, you also might want to pay off some of those debts before purchasing real estate, even with a physician mortgage loan. It all depends on the interest rates and terms. Check out this post on debt from Future Proof M.D. for more info and a few options.
Think about it and choose the path that is right for you.
9. You need to educate yourself
Our physician mortgage loan FAQ will answer more of your burning questions about physician loans specifically, but it’s critical you learn as much as you can about the finance and home buying process. This is the biggest purchase you’ll ever make, and it pays dividends to know what you’re doing. At least know the basics. You’ll probably buy another house in your lifetime, and you can continue to build on your home buying knowledge with every purchase.
Heck. You may even be able to pass this knowledge down to your friends, family or children one day. It’s important stuff.
Please comment below and let me know if there are other things you’d like to know. If you spot any mistakes, point them out, and I’ll correct them.
My best advice to you is to give Bill Rapp, the Mortgage Viking, a call today to discuss the next steps: 281-222-0433.
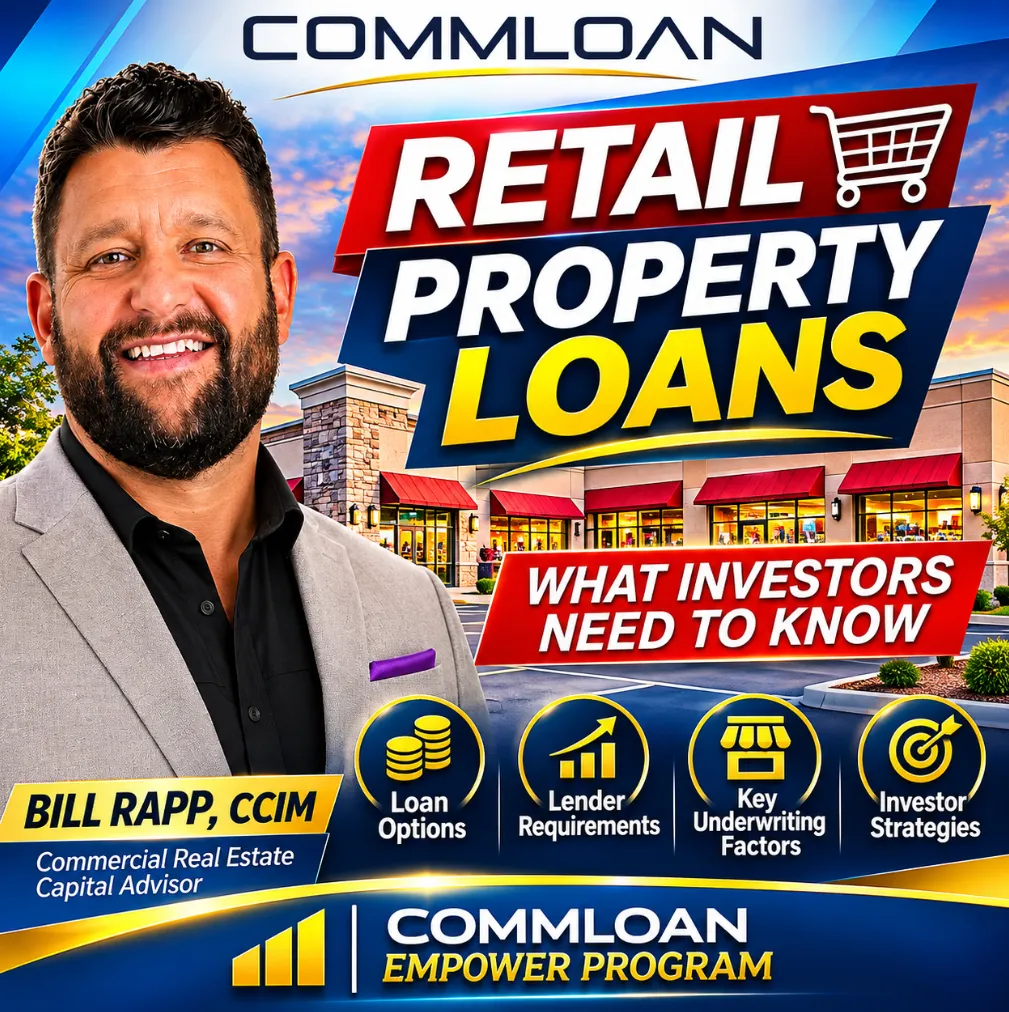
🏬 Retail Property Loans: Investor Financing Guide 💰
🏬 Retail Property Loans: Investor Financing Guide 💰
💵 Retail Real Estate Financing: Loan Options 🏢
________________________________________________________________________________
Retail Property Loans: What Investors Need to Know
Retail real estate can offer investors attractive income opportunities, long-term tenant relationships, and portfolio diversification. However, financing a retail property requires more than finding a lender willing to offer a commercial mortgage.
Whether you're purchasing a neighborhood shopping center, acquiring a single-tenant net-leased property, refinancing a retail strip center, or financing an owner-occupied storefront, understanding retail property loans can help you make more informed investment decisions.
Commercial lenders evaluate retail properties differently based on tenant quality, lease structures, cash flow, occupancy, location, and property condition.
In this guide, we'll explore retail real estate financing options, underwriting requirements, loan-to-value ratios, debt service coverage, and strategies for securing competitive financing.
What Is a Retail Property Loan?
A retail property loan is a commercial real estate mortgage used to purchase, refinance, renovate, or develop property intended for retail business operations.
Common retail property types include:
Single-tenant retail buildings: Freestanding properties occupied by one business, such as a pharmacy, restaurant, or national retailer.
Neighborhood shopping centers: Multi-tenant retail centers serving surrounding residential communities.
Strip centers: Smaller retail buildings featuring multiple storefronts.
Grocery-anchored centers: Shopping centers anchored by supermarkets or other high-traffic retailers.
Retail pad sites: Freestanding properties within larger retail developments.
Owner-occupied retail properties: Buildings purchased by business owners to operate their own businesses.
Each category carries different risks and underwriting considerations.
For example, a shopping center with ten diversified tenants may present a different risk profile than a single-tenant building dependent on one operator.
Understanding those differences is essential when selecting a financing strategy.
1. Retail Property Financing Options
Commercial real estate investors have several potential financing solutions.
Conventional Bank Loans
Traditional banks remain an important source of retail property financing.
These loans may offer competitive interest rates and flexible structures for established borrowers purchasing stabilized properties.
Typical characteristics include:
Loan-to-value ratios often around 65%–75%.
Amortization periods commonly between 20 and 25 years.
Loan terms frequently ranging from 3 to 10 years.
Personal guarantees often required.
Strong emphasis on borrower financial strength and property cash flow.
Some lenders may offer different terms depending on sponsorship, tenant quality, deposit relationships, and market conditions.
Best suited for: Stabilized shopping centers, established retail investors, and owner-users with strong financial profiles.
Commercial Mortgage-Backed Securities (CMBS) Loans
CMBS financing may be appropriate for larger stabilized retail investments.
These loans are typically structured around property-level cash flow and institutional underwriting standards.
Potential advantages include longer fixed-rate terms, nonrecourse structures subject to customary carve-outs, and financing for larger investment properties.
However, investors should understand that CMBS loans may include substantial prepayment restrictions, defeasance or yield maintenance, cash management requirements, and more rigid servicing procedures.
Best suited for: Larger stabilized retail properties with predictable income and experienced sponsorship.
Debt Service Coverage Ratio (DSCR) Loans
DSCR-focused commercial mortgage programs emphasize whether a property's income supports its debt obligations.
The basic formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
For example, if a retail center generates $180,000 in annual net operating income and has $135,000 in annual mortgage payments:
DSCR = $180,000 ÷ $135,000 = 1.33
A 1.33 DSCR means the property generates approximately $1.33 in net operating income for every $1.00 of annual debt service.
Many lenders target DSCR levels around 1.20–1.35 or higher for stabilized retail, although actual requirements depend on the program and property.
Best suited for: Income-producing retail investments where cash flow is a central underwriting consideration.
SBA 7(a) and SBA 504 Loans
Small business owners purchasing retail real estate for their own operations may qualify for SBA-backed financing.
Two major programs are:
SBA 7(a)
Can finance eligible real estate acquisitions and certain related business needs.
May offer terms up to 25 years for qualifying real estate.
Often permits lower equity contributions than conventional commercial mortgages, subject to eligibility and underwriting.
Has a standard maximum loan amount of $5 million.
SBA 504
Designed primarily for eligible fixed-asset financing.
Often uses a structure involving a bank lender, a Certified Development Company, and borrower equity.
A typical structure may involve 50% bank financing, 40% CDC financing, and 10% borrower equity, with higher contributions in certain situations.
The CDC/SBA portion has separate eligibility and project limits.
Importantly, SBA financing generally is not intended for passive investment in rental retail property. The operating business must meet applicable owner-occupancy and eligibility requirements.
Best suited for: Qualified retailers, restaurateurs, service businesses, and other operating companies purchasing their own commercial facilities.
Bridge Loans
Bridge financing can help investors acquire or reposition properties that do not currently meet conventional underwriting standards.
Examples include:
Retail centers with significant vacancy.
Properties requiring major renovations.
Shopping centers undergoing tenant replacement.
Acquisitions requiring accelerated closing.
Assets awaiting stabilization before permanent refinancing.
Bridge loans often carry higher interest rates, shorter terms, and greater refinancing risk than permanent commercial mortgages.
The most important consideration is the exit strategy.
Before accepting bridge financing, investors should determine whether the property can realistically qualify for permanent financing or be sold before the loan matures.
2. How Lenders Underwrite Retail Properties
Retail underwriting involves more than the borrower's credit score.
Lenders analyze the property as an income-producing business asset.
Net Operating Income
Net operating income, or NOI, represents property revenue after ordinary operating expenses but before debt service, income taxes, depreciation, and amortization.
NOI = Effective Gross Income − Operating Expenses
For retail properties, lenders review rental income, reimbursements, vacancies, property taxes, insurance, management fees, repairs, and reserves.
A property with strong rental income can still struggle to qualify if operating expenses are unusually high.
Tenant Credit Quality
Tenant financial strength can materially influence loan terms.
Lenders may distinguish between:
National investment-grade retailers.
Established regional chains.
Local independent businesses.
Franchise operators.
Newly established businesses.
A recognizable brand name does not automatically mean the lease is guaranteed by a financially strong corporate entity.
For example, a restaurant operating under a national franchise brand may be leased to an individual franchisee rather than the franchisor.
Lenders evaluate the actual lease obligor and any guarantor.
Lease Structure
Retail properties frequently use one of several lease structures.
Triple Net (NNN): Tenants reimburse or directly pay certain property expenses, often including taxes, insurance, and common-area maintenance.
Modified Gross: Landlords and tenants divide operating expenses according to the lease.
Gross Lease: The landlord generally pays more operating expenses from the stated rental income.
The exact contractual terms matter more than the lease label.
Investors should evaluate expense reimbursements, caps, exclusions, maintenance responsibilities, and potential collection shortfalls.
Lease Expiration and Rollover
A property's weighted average lease term, or WALT, helps lenders evaluate future rental income stability.
Consider two shopping centers with identical current NOI.
One has tenants committed for another eight years.
The other has half its tenants expiring within eighteen months.
Even with identical current income, the second property may present greater rollover and refinancing risk.
Lenders may require additional reserves or lower leverage when significant lease expirations are approaching.
Location and Retail Demand
Location remains a major component of retail financing.
Lenders consider:
Population and household income.
Traffic counts and accessibility.
Visibility and signage.
Parking availability.
Surrounding residential development.
Competing retail inventory.
Tenant demand and market rents.
Retail centers in established or expanding trade areas may benefit from stronger leasing prospects, but location alone does not guarantee financing approval.
3. How Much Can You Borrow on Retail Real Estate?
Loan proceeds generally depend on several constraints:
1.Loan-to-value ratio.
2.Debt service coverage.
3.Borrower financial strength.
4.Property condition and tenant concentration.
5.Loan program and lender guidelines.
Loan-to-Value Ratio
Loan-to-value measures the loan amount relative to the property's appraised value.
LTV = Loan Amount ÷ Property Value
Suppose an investor purchases a retail strip center for $2 million.
At 70% LTV:
Maximum loan based on value = $1,400,000
The investor would need approximately $600,000 in equity before closing costs, reserves, and other transaction expenses.
However, qualifying for 70% LTV does not guarantee a $1.4 million loan.
The property's cash flow must also support the proposed debt.
DSCR Can Reduce Loan Proceeds
Suppose the lender requires a minimum DSCR of 1.25.
If the property's NOI is $150,000:
Maximum annual debt service = $150,000 ÷ 1.25 = $120,000
The lender must structure the loan so annual principal and interest payments do not exceed that amount, subject to its underwriting methodology.
The resulting loan amount may be lower than the amount suggested by the property's appraised value.
The practical lesson: Your maximum commercial mortgage is often determined by the most restrictive underwriting constraint.
4. Retail Property Financing Example
Let's evaluate a hypothetical neighborhood shopping center.
Property Metric | Amount |
Purchase price | $3,000,000 |
Annual gross rental revenue | $330,000 |
Vacancy and collection allowance | $15,000 |
Operating expenses | $105,000 |
Net operating income | $210,000 |
Proposed loan amount | $2,100,000 |
Loan-to-value ratio | 70% |
Illustrative interest rate | 7.00% |
Amortization | 25 years |
Annual debt service | Approximately $178,100 |
Debt service coverage ratio | Approximately 1.18 |
Illustrative assumptions only; not a current rate quote or financing offer.
At a 1.18 DSCR, this property may fall below a lender's minimum coverage requirement.
If the lender requires a 1.25 DSCR, the maximum annual debt service would be:
$210,000 ÷ 1.25 = $168,000
At the same illustrative interest rate and amortization, the DSCR-constrained loan amount would be approximately $1.98 million.
That is roughly $120,000 less than the initial 70% LTV request.
This example illustrates why investors should evaluate cash flow before relying on a lender's advertised maximum leverage.
5. Common Retail Financing Challenges
High Tenant Concentration
A single tenant accounting for 60% of a shopping center's income creates greater concentration risk than a more diversified rent roll.
Lenders may respond by reducing leverage or requiring stronger reserves.
Short Remaining Lease Terms
A tenant approaching expiration may create uncertainty about future occupancy and rental rates.
Lease renewals or extensions can sometimes improve financing options.
Deferred Maintenance
Roof replacements, parking lot repairs, HVAC systems, and building renovations can affect lender confidence.
A property condition assessment may identify required repairs and capital reserves.
Vacant Retail Space
Vacancy reduces current income and may increase leasing costs.
Investors should account for tenant improvement allowances, leasing commissions, downtime, and free rent when evaluating a lease-up strategy.
Environmental Concerns
Certain retail uses, including dry cleaners, automotive services, and former fuel-related operations, may require additional environmental due diligence.
Lenders commonly require an appropriate environmental assessment before closing.
6. Documents Needed for a Retail Property Loan
Preparing a complete financing package can reduce underwriting delays.
Typical lender requests include:
Current rent roll and tenant lease abstracts.
Copies of executed leases and amendments.
Trailing 12-month operating statements.
Year-to-date profit and loss statements.
Property tax and insurance information.
Purchase contract or current loan statement.
Borrower financial statements and liquidity verification.
Entity formation documents.
Property photographs and capital improvement history.
Business financials for owner-occupied transactions.
Depending on the lender, additional documents may include tenant financial statements, estoppel certificates, environmental reports, property condition assessments, and an appraisal.
A well-organized loan package can make it easier to compare lender proposals and identify potential underwriting concerns early.
7. How to Improve Your Retail Property Loan Terms
Investors can take several practical steps before applying for financing.
Improve occupancy and collections. Stable, documented income can support stronger underwriting.
Extend important tenant leases. Longer commitments from financially sound tenants may reduce rollover risk.
Document expense reimbursements. Accurate NNN reconciliations can help lenders verify sustainable NOI.
Maintain adequate liquidity. Post-closing reserves can improve borrower strength.
Prepare a realistic business plan. For transitional properties, show leasing assumptions, improvement budgets, and a credible refinance or sale strategy.
Compare multiple capital sources. Banks, credit unions, CMBS lenders, debt funds, and other commercial mortgage providers have different credit requirements.
The lowest advertised interest rate is not always the best financing option.
Loan term, amortization, prepayment provisions, guarantees, recourse, reserve requirements, and closing certainty should all factor into the decision.
8. Why Work With a Commercial Mortgage Broker?
Retail real estate financing is not one-size-fits-all.
A neighborhood strip center with local tenants may fit a community bank's lending criteria, while a larger stabilized shopping center may be better suited to institutional financing.
An owner-occupied retail business may qualify for SBA financing, while a vacant property requiring renovation may need a bridge loan.
Working with a commercial mortgage broker can help investors evaluate multiple financing structures rather than relying exclusively on one institution's lending guidelines.
Through the CommLoan Empower Program, I help commercial real estate investors and business owners navigate commercial mortgage financing options, evaluate lender requirements, and prepare transactions for underwriting.
My approach emphasizes matching the property, borrower, investment strategy, and anticipated exit with an appropriate capital source.
Frequently Asked Questions About Retail Property Loans
What is the typical down payment for a retail property loan?
Many conventional investment-property loans require approximately 25%–35% equity, although requirements vary. Qualified SBA owner-occupied transactions may permit lower contributions.
Can I finance a retail property with vacant units?
Yes, but significant vacancy may limit conventional financing options. Bridge financing or other transitional loan programs may be more appropriate.
Are retail property loans available for first-time investors?
Potentially. Lenders may place greater emphasis on borrower liquidity, experience, credit, outside income, property management, and property cash flow.
Can I refinance a retail shopping center?
Yes. Refinancing may be used to replace maturing debt, modify loan terms, or potentially access equity, subject to valuation and underwriting.
Do retail property loans require personal guarantees?
Many bank loans require guarantees. Certain institutional or securitized programs may offer nonrecourse financing subject to customary exceptions.
Can I use an SBA loan to buy a strip center?
Only when the transaction meets SBA eligibility requirements, including applicable operating-business occupancy rules. SBA programs generally cannot be used simply to acquire passive rental investment property.
Final Thoughts: Structure Your Retail Property Financing Before You Buy
Retail real estate can provide meaningful investment opportunities, but financing decisions directly affect cash flow, leverage, risk, and long-term returns.
Before purchasing or refinancing a retail property, evaluate the tenant roster, lease expirations, NOI, DSCR, capital expenditures, and available financing structures.
A successful transaction begins with understanding both the property and the lender's underwriting requirements.
Ready to explore retail property financing?
I'm Bill Rapp, CCIM, and through the CommLoan Empower Program, I work with commercial real estate investors and business owners seeking financing solutions for retail, industrial, office, multifamily, and other commercial properties.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246